Single-asset evidence report · By CoinNudge Research · · Guide updated 2026-10-03 · 20 min read
What is XRP coin, and is it worth holding?
XRP is the native currency of the XRP Ledger. It pays transaction costs and can be used as a bridge asset, but owning XRP is not owning Ripple or its payment business. For a holding decision, a credible XRP holding case needs independently measured XRP-specific payment demand and a dated escrow/float analysis; Ripple business growth by itself is insufficient. In the frozen Binance spot daily-open window ending September 25, 2026, XRP returned +46.3% versus BTC +40.5%; across 57 earlier monthly starts, its median was −1.8% and 20/57 beat BTC. Overlapping history is not a future win rate or personal buy call.
Inspect all historical starts · Check current market context
What should investors know about XRP?
- XRP gained +46.3% in the last frozen 90-day window; this differs from its historical monthly-start median −1.8%.
- 20/57 complete historical 90-day starts beat BTC, while 50/57 had a deeper daily-open drawdown.
- A credible XRP holding case needs independently measured XRP-specific payment demand and a dated escrow/float analysis; Ripple business growth by itself is insufficient.
XRP, Ripple and the XRP Ledger: what exactly do you own?
XRP is the native currency of the XRP Ledger. It pays transaction costs and can be used as a bridge asset, but owning XRP is not owning Ripple or its payment business.
The three names identify different things: XRP is the native currency, XRPL is the ledger, and Ripple is a company with its own business and inventory. Purchasing XRP buys the asset, not a share of the company.
The holding question therefore follows XRP-specific demand and accessible supply, not every payment headline. The 57 paired 90-day spot observations below provide historical risk evidence; they do not count payment users or certify Ripple's future sales.
| XRP at a glance | Dated evidence | How to read it |
|---|---|---|
| Documented token role | Transfers native XRP and pays XRPL transaction fees | Not an automatic claim on every project activity |
| Last frozen 90-day spot return | +46.3% | BTC on the same UTC dates: +40.5% |
| Historical 90-day monthly median | −1.8% | 57 overlapping complete starts, not a forecast |
| Current circulating supply | 62,879,209,849 | CoinGecko response updated 2026-09-26T10:12:20.000Z |
Verify: XRP Ledger: what is XRP? · XRPL escrow mechanics · XRPL transaction costs
Does owning XRP give you a claim on Ripple payment revenue?
No: XRP ownership does not grant Ripple equity, dividends or a claim on the company's payment revenue. It gives the native asset used in supported ledger transactions.
A payment or issued asset on XRPL can create some network-fee demand without requiring a customer to hold the full transferred value in XRP. Before valuing a payments story, name the specific route, the bridge asset and who retains inventory.
Participation in the ecosystem also differs from holding a corporate voting share. Verify the relevant ledger rule or product terms directly; a company announcement is not a new contractual benefit for an XRP wallet.
| Who owns what | Documented role or participation | What cannot be inferred |
|---|---|---|
| XRP holder | Transfers native XRP and pays XRPL transaction fees | No Ripple equity, dividends or claim on company payment revenue |
| Ripple company | Develops products and holds its own XRP inventory | Company sales are not XRP holder distributions |
| XRPL user | May use XRP, trust-line assets or other features depending on route | Ledger activity is not uniformly XRP buy-and-hold demand |
Verify: XRP Ledger: what is XRP? · XRPL escrow mechanics · XRPL transaction costs
Do Ripple payments actually create demand for XRP?
Ripple payments can create XRP demand when a specific route actually uses and retains XRP, but company adoption does not automatically establish that demand. This release has not independently measured the route-level inventory series; a headline payment volume is not a tokenholder cash flow.
XRP Ledger supports native XRP transfers, escrow and other issued assets. A payment can use XRP as a bridge, but not every payment on the ledger or every Ripple business product forces the customer to buy and retain XRP. Document the specific route and XRP balances before converting business adoption into a token-demand estimate.
Ripple is a separate company and holds XRP, some locked in on-ledger escrows. An eligible escrow release makes tokens accessible to its recipient; it does not prove all tokens were immediately sold. Compare completed escrow transactions, re-locking and exchange flows at the same dates, not an old headline monthly ceiling.
A bridge-demand scenario needs both the amount settled through XRP and how long intermediaries keep XRP inventory. The same units can be reused, so throughput does not equal a permanently held balance. Verify route-level balances and timing before applying a volume multiple to XRP valuation; this release has not independently measured that inventory series.
XRP's dated price experiment below measures spot returns and drawdown paths, not the causal contribution of project adoption. The release has no independently frozen continuous operating-economics series that completes this value-capture test.
Verify: XRP Ledger: what is XRP? · XRPL escrow mechanics · XRPL transaction costs
What do Ripple escrow releases mean for XRP circulating supply?
Ripple escrow changes access to existing XRP rather than minting new XRP. Eligible releases, completed releases, re-locking and sales must be distinguished before forecasting float; the provider circulation value is not an escrow audit.
CoinGecko’s separate 2026-09-26T10:12:20.000Z response reports 62,879,209,849 circulating XRP out of 99,985,622,230 total and 100,000,000,000 maximum. These are provider classifications, not an audit of custodian balances or a schedule of future exchange selling.
All XRP was created at ledger inception; normal transactions burn small XRP fees rather than mint new XRP. Ripple escrow is a release and custody issue, not new protocol issuance. The provider circulating field is a methodology-dependent estimate; reconcile actual escrow inventory, released amounts and Ripple sales before forecasting tradable float.
For XRP, trace escrow eligibility, completed release, any re-locking, recipient inventory transfer and independently evidenced selling as separate stages. These concern existing XRP, not fresh mining issuance. A maximum-minus-circulating gap is not a monthly sale estimate; a wallet transfer to a venue is not itself proof of a completed customer sale. Unattributed inventory remains an explicit gap.
| XRP supply field | Frozen provider value | Reading rule |
|---|---|---|
| Circulating supply | 62,879,209,849 | CoinGecko provider definition at 2026-09-26T10:12:20.000Z |
| Total supply | 99,985,622,230 | May differ from circulating and maximum supply |
| Maximum supply | 100,000,000,000 | Missing is not zero and not equal to total supply |
| Reported circulating / maximum | 62.9% | Not a dated release schedule or tradable-float audit |
Verify: Frozen original supply response · XRP Ledger: what is XRP? · XRPL escrow mechanics · XRPL transaction costs
XRP tokenomics: escrow access, fee burns and holder rights
XRP escrow releases make existing inventory transferable; they do not mint new XRP or prove an exchange sale. Ordinary ledger fees destroy a small amount of XRP. Neither payment adoption nor ownership of XRP gives a holder Ripple company equity or a share of company revenue.
To assess dilution and demand, separate escrow eligibility, executed completion, re-locking and actual distribution, then compare those transfers with payment-route use and executable exchange depth at matching observation times. The provider circulation snapshot below is not an escrow-account audit; unknown wallet destinations remain unknown.
| Token-economics dimension | Documented mechanism or attributed claim | What remains unproven / investor implication |
|---|---|---|
| Origin and supply | XRP was created at ledger inception; ordinary transaction fees destroy a small amount rather than issuing new XRP. | The CoinGecko circulating field is provider-defined and differs from an escrow-account audit. |
| Escrow and float | Ripple holds XRP in dated on-ledger escrows; eligibility, executed EscrowFinish, re-locking and market sale are separate events. | Do not count the whole eligible tranche as exchange selling. |
| Use and rights | XRP can pay network costs and serve as a bridge in relevant payment routes. | Ripple company revenue and corporate equity do not automatically accrue to XRP holders. |
| Investor check | Reconcile escrow completion, Ripple inventory, actual payment routes and exchange depth at matching timestamps. | A payments headline alone does not measure XRP held or purchased. |
Verify: XRPL XRP overview · XRPL escrow mechanics
Did XRP outperform Bitcoin—or only in selected time windows?
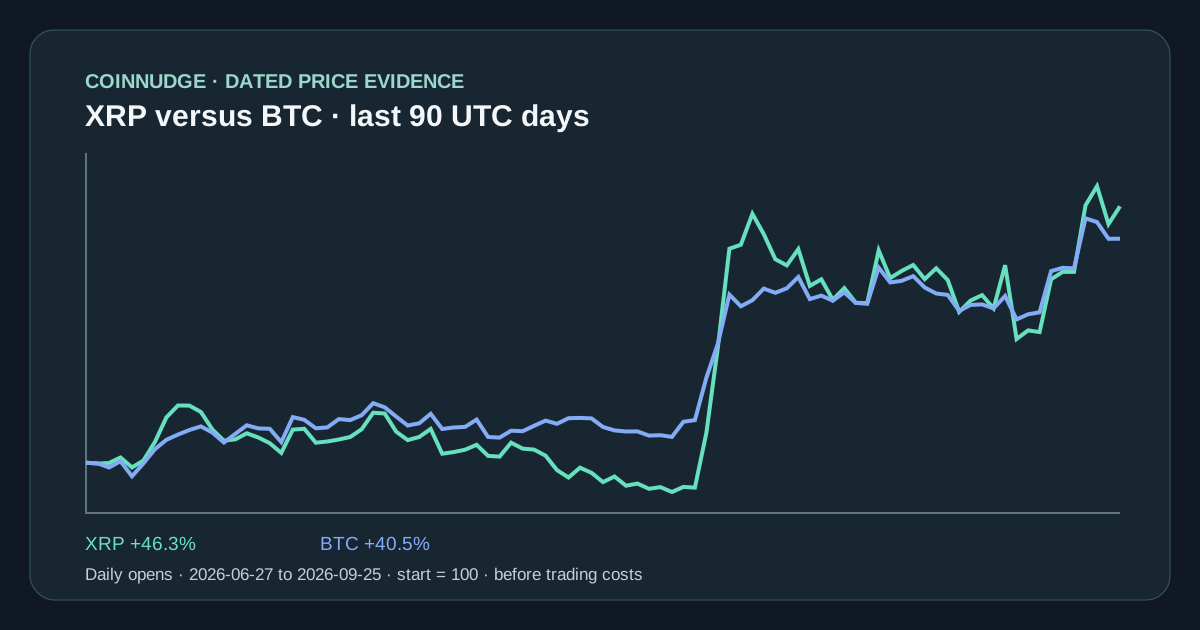
At the September 25 UTC daily-open endpoint, XRP returned +46.3% over 90 days versus BTC +40.5% on exactly the same days. The 365-day XRP path was −47.5% versus BTC −25.5%. These different windows are one dated path each—not five independent tests or a prediction.
The 90-day chart plots all 91 matched UTC daily opens from 2026-06-27 to 2026-09-25, normalized to 100 on the first day. A later CoinGecko price or 24-hour change may differ because the venue, market window and timestamp differ. The table reports the actual shared-start comparison rather than mixing unrelated provider percentages.
| Matched holding window | XRP spot return | BTC spot return | XRP minus BTC / status |
|---|---|---|---|
| 7 days | +18.4% | +10.5% | 7.9 pp |
| 30 days | +7.0% | +7.5% | -0.5 pp |
| 90 days | +46.3% | +40.5% | 5.8 pp |
| 180 days | +15.1% | +27.2% | -12.1 pp |
| 365 days | −47.5% | −25.5% | -22.0 pp |
Verify: Full dated path and methods
Across 57 monthly entry points, when did XRP beat BTC?
Across the frozen matched 90-day monthly starts, XRP's median return was −1.8% versus BTC +1.9%, and 20/57 starts beat BTC. That is descriptive historical evidence, not a future success probability; the full overlapping sample, dependence check and opposing cases appear below.
We prespecified every first day of a month after the Binance listing had a full prior month through June 2026. Of 57 candidate 90-day starts, 57 had a complete 91-daily-open XRP/BTC pair and 0 were excluded for missing daily opens. The XRP median endpoint was −1.8%, BTC's was +1.9%; XRP beat BTC in 20/57. Those windows overlap and must not be treated as 57 independent win-probability trials.
XRP had a deeper daily-open peak-to-trough drawdown in 50/57 matched windows. The lower 10th-percentile XRP endpoint was −31.2% and the upper 90th percentile +38.3%. Every-third-month sensitivity has only 19 observations and 6 BTC-beating starts; it is a dependence check, not a statistically powered forecast.
The worst BTC-relative start was 2023-12-01: −5.2% for XRP against +65.5% BTC, with −25.1% asset drawdown. A counterexample is 2024-11-01: +502.1% for XRP versus +47.6% BTC. Showing both prevents the current rally or a past collapse from becoming the whole story.
| 90-day monthly cohort measure | XRP | BTC / paired comparison | Interpretation |
|---|---|---|---|
| Complete starts | 57 | 57 | Same UTC dates and 91 daily opens |
| Median endpoint | −1.8% | +1.9% | Not an expected future return |
| 10th / 90th percentile | −31.2% / +38.3% | −24.9% / +47.8% | Descriptive tail range |
| Outperformed BTC | 20/57 | — | Overlapping monthly windows |
| Deeper path drawdown | 50/57 | — | Measured at daily opens only |
| Every-third-month check | 6/19 | — | Small non-overlap sensitivity |
Verify: All matched starts and excluded candidates · Frozen calculation contract
Which XRP 90-day holding periods won, and which lost?
Both winning and losing XRP windows are shown: all 57 eligible same-date XRP/BTC 90-day observations are visible chronologically below. The worst BTC-relative start was 2023-12-01: −5.2% for XRP against +65.5% BTC, with −25.1% asset drawdown. A counterexample is 2024-11-01: +502.1% for XRP versus +47.6% BTC. These are contrasting examples from the complete table, not independent future scenarios. A first-of-month start is the frozen sample design, not a suggested buying schedule.
Compare terminal return with interim drawdown in each row. Daily-open paths can understate intraday harm; fees, spreads, slippage, tax, staking and leverage are excluded. The complete input CSV and exclusion ledger are available for independent recalculation.
| UTC start | XRP 90d | BTC 90d | XRP − BTC | XRP path drawdown |
|---|---|---|---|---|
| 2021-10-01 | −14.3% | +6.0% | -20.3 pp | −39.0% |
| 2021-11-01 | −44.5% | −37.7% | -6.8 pp | −53.4% |
| 2021-12-01 | −21.8% | −24.2% | +2.4 pp | −40.2% |
| 2022-01-01 | −1.8% | −1.5% | -0.3 pp | −30.5% |
| 2022-02-01 | −1.7% | +0.0% | -1.7 pp | −33.3% |
| 2022-03-01 | −50.2% | −31.7% | -18.4 pp | −55.8% |
| 2022-04-01 | −59.6% | −55.8% | -3.8 pp | −63.5% |
| 2022-05-01 | −37.1% | −36.8% | -0.2 pp | −52.4% |
| 2022-06-01 | −20.9% | −36.2% | +15.3 pp | −27.1% |
| 2022-07-01 | +35.3% | −2.7% | +37.9 pp | −17.2% |
| 2022-08-01 | +24.0% | −10.7% | +34.7 pp | −16.2% |
| 2022-09-01 | +21.5% | −18.0% | +39.5 pp | −37.4% |
| 2022-10-01 | −28.7% | −14.4% | -14.4 pp | −37.4% |
| 2022-11-01 | −10.9% | +15.9% | -26.8 pp | −34.2% |
| 2022-12-01 | −7.7% | +34.8% | -42.6 pp | −17.1% |
| 2023-01-01 | +58.6% | +72.1% | -13.5 pp | −15.2% |
| 2023-02-01 | +14.5% | +21.4% | -6.8 pp | −17.2% |
| 2023-03-01 | +31.5% | +19.9% | +11.6 pp | −22.5% |
| 2023-04-01 | −11.7% | +7.0% | -18.6 pp | −21.7% |
| 2023-05-01 | +51.4% | +0.4% | +51.0 pp | −14.4% |
| 2023-06-01 | +4.5% | +1.9% | +2.6 pp | −38.3% |
| 2023-07-01 | +7.8% | −11.3% | +19.1 pp | −42.1% |
| 2023-08-01 | −20.3% | +18.1% | -38.4 pp | −32.9% |
| 2023-09-01 | +19.2% | +45.9% | -26.7 pp | −19.0% |
| 2023-10-01 | +21.0% | +56.0% | -35.0 pp | −19.0% |
| 2023-11-01 | −10.7% | +25.0% | -35.8 pp | −28.1% |
| 2023-12-01 | −5.2% | +65.5% | -70.7 pp | −25.1% |
| 2024-01-01 | +0.9% | +64.6% | -63.7 pp | −20.1% |
| 2024-02-01 | −0.5% | +42.5% | -43.0 pp | −33.8% |
| 2024-03-01 | −10.7% | +10.7% | -21.4 pp | −33.8% |
| 2024-04-01 | −24.9% | −14.4% | -10.4 pp | −25.3% |
| 2024-05-01 | +20.2% | +10.1% | +10.2 pp | −22.5% |
| 2024-06-01 | +8.5% | −12.1% | +20.7 pp | −22.1% |
| 2024-07-01 | +28.9% | +4.9% | +24.0 pp | −22.1% |
| 2024-08-01 | −15.2% | +12.5% | -27.7 pp | −21.7% |
| 2024-09-01 | +218.0% | +65.3% | +152.7 pp | −21.7% |
| 2024-10-01 | +242.5% | +48.0% | +194.5 pp | −23.1% |
| 2024-11-01 | +502.1% | +47.6% | +454.5 pp | −24.4% |
| 2024-12-01 | +9.9% | −12.5% | +22.4 pp | −34.8% |
| 2025-01-01 | +0.3% | −11.8% | +12.1 pp | −38.6% |
| 2025-02-01 | −27.1% | −5.8% | -21.3 pp | −40.8% |
| 2025-03-01 | +4.6% | +25.2% | -20.6 pp | −38.9% |
| 2025-04-01 | +5.6% | +31.3% | -25.7 pp | −21.9% |
| 2025-05-01 | +42.8% | +25.3% | +17.5 pp | −21.9% |
| 2025-06-01 | +29.7% | +3.6% | +26.1 pp | −22.0% |
| 2025-07-01 | +28.2% | +4.7% | +23.5 pp | −22.7% |
| 2025-08-01 | −15.6% | −5.0% | -10.7 pp | −30.9% |
| 2025-09-01 | −20.7% | −16.1% | -4.6 pp | −37.5% |
| 2025-10-01 | −35.0% | −23.5% | -11.5 pp | −40.5% |
| 2025-11-01 | −28.0% | −22.8% | -5.2 pp | −28.5% |
| 2025-12-01 | −36.1% | −25.9% | -10.3 pp | −48.3% |
| 2026-01-01 | −27.2% | −22.1% | -5.1 pp | −48.3% |
| 2026-02-01 | −15.9% | −0.6% | -15.2 pp | −26.3% |
| 2026-03-01 | −3.4% | +9.7% | -13.0 pp | −15.3% |
| 2026-04-01 | −21.0% | −11.8% | -9.3 pp | −29.7% |
| 2026-05-01 | −21.5% | −16.2% | -5.3 pp | −30.0% |
| 2026-06-01 | +4.8% | +6.2% | -1.4 pp | −25.5% |
Can XRP spot liquidity absorb a real purchase or sale?
A quoted XRP price does not guarantee your order can buy or exit there. This report has one dated Binance order-book sample, separate from historical daily turnover; execution requires a fresh route-specific book and cost check.
The historical XRP/USDT Binance spot candles show $210,405,007 median daily quote turnover across 30 complete UTC days. This is a transaction-flow measure, not cash available at a specific bid or ask. It also excludes other exchanges and market-maker obligations.
A separate CoinNudge Binance book sample observed at 2026-09-26T10:11:09.229Z shows 0.65 bps quoted spread and $4,161,327 returned depth within ±1% of mid. The modelled $10,000 buy slippage is 0.32 bps before fees and latency. Recheck the live book and your actual venue; this is one snapshot, not guaranteed execution.
Before an actual XRP order, match the pair, venue and observation time, then estimate the buy from asks and the planned exit from bids at the intended size. Add fees and any transfer costs; one basis point is 0.01%. If the returned levels cannot fill the size, or access/data is delayed, reduce the planned exposure or wait for adequate evidence—not extrapolate the historical turnover into depth.
| Liquidity or execution measure | Dated observed value | Limit |
|---|---|---|
| 30-day Binance spot median daily quote turnover | $210,405,007 | 30 complete archived UTC days; turnover ≠ executable depth |
| Sampled bid/ask spread | 0.65 bps | One Binance book observation; can change by the second |
| Visible depth within ±1% of mid | $4,161,327 | Returned 500 levels per side only |
| Simulated $10k buy / sell slippage | 0.32 / 0.32 bps | Excludes fees, latency and later book changes |
Verify: Frozen top-30 order-book source · Current market-depth research
Do payment-adoption headlines prove demand for XRP itself?
Payment-adoption headlines do not prove demand for XRP itself. Separate a Ripple company milestone from a route that uses XRP, then check actual asset balances or transactions rather than social enthusiasm.
Search-trending lists and public discussions show attention to XRP at the September 26 review. The cited lists are dynamic, and this release did not freeze a defensible unique-person or social-mention count. Attention is not a count of buyers, tokenholder rights or durable usage.
The recurring investor debate is whether payment adoption and Ripple news benefit XRP itself. Separate company milestones, ledger usage, bridge-asset usage and token supply before using social optimism as evidence.
To use XRP discussion constructively, choose one factual claim, follow its direct source, note the date and beneficiary, and compare it with the rights and supply checks in this report. An unsupported promotion remains attention evidence; it is not converted into a holder-benefit claim or buying score.
Verify: Cross-platform social directory · CoinGecko short-window search attention · XRP Ledger: what is XRP? · XRPL escrow mechanics · XRPL transaction costs
Is XRP worth holding when escrow supply meets uncertain payment demand?
There is no unconditional yes from this evidence. A credible XRP holding case needs independently measured XRP-specific payment demand and a dated escrow/float analysis; Ripple business growth by itself is insufficient. The last frozen 90-day return was +46.3%, while the median of 57 earlier monthly-start windows was −1.8%; 20/57 beat BTC. These overlapping historical paths describe risk, not the chance of a profitable hold from today.
Evidence that would strengthen a holding thesis: Verifiable XRP-specific bridge usage rises, released float is absorbed without weakening depth, and the value proposition can be measured independently of Ripple equity stories. Evidence that would weaken or end it: Payment headlines mainly concern products that do not require XRP, or released treasury inventory outpaces real token demand.
A holder should state a time horizon, position size, acceptable drawdown and specific facts that would trigger a reassessment. Revision trigger for this report: New primary evidence on XRP use in payment routes, escrow balances or Ripple sales changes the thesis. The checklist is not a personal recommendation, target price or promise that the next 90 days resemble a prior cohort.
For an XRP holding candidate, write the actual source of token demand, the escrow inventory relevant to the chosen horizon and the current exit route. A company partnership without route-level XRP evidence remains a hypothesis. If a release is only eligible, do not call it a sale; if live sell-side depth or venue access fails the order check, postpone execution even when historical turnover was high.
| Holding decision check | Evidence to verify | Why it matters |
|---|---|---|
| Tokenholder benefit | Transfers native XRP and pays XRPL transaction fees | No Ripple equity, dividends or claim on company payment revenue |
| Future tradable supply | Official allocation dates and actual transfers | Provider float alone is not a sell forecast |
| Ability to exit | Fresh bid/ask depth plus fees and latency | Historical turnover is not a fill guarantee |
| Opportunity cost versus BTC | 57 complete historical paired starts plus current common window | Absolute gains can still lag BTC |
| Thesis invalidation | New primary evidence on XRP use in payment routes, escrow balances or Ripple sales changes the thesis. | A stated reason to reassess is more useful than an indefinite hold slogan |
Verify: Frozen XRP/BTC price study · Complete XRP monthly observation ledger · XRP Ledger: what is XRP? · XRPL escrow mechanics · XRPL transaction costs
How can you reproduce every XRP-versus-BTC return and drawdown?
Reproduce XRP's spot results from the matched asset/BTC daily inputs, complete observation CSV, exclusions and frozen JSON below. Keep the original calculation version and cutoff: the October 3, 2026 edit clarifies decisions and subquestions, not a recalculation or a fresh market release.
Calculation hot-coin-spot-paths-1.0; historical cutoff 2026-09-25 UTC. The archived candle ledger preserves event_time, observed_at and ingested_at. Historical fills may have been collected retrospectively; this study does not claim every bar was available to CoinNudge on its original event date.
Recent returns use the same UTC daily-open start and endpoint for XRP and BTC with every intermediate day present. The monthly study buys at the first-day open and exits at the day-90 open, with 91 complete daily opens per pair; maximum drawdown is min(path / prior running peak − 1). It assumes no costs or dividends. The asset and BTC daily input CSVs enable independent numerical replay. Candidate and exclusion counts, input SHA-256 84110f05dc9a972d15480997f8fc775ae5a745dac1a14a7bc85c8822dbe1b8fe of the complete normalized archive objects, and output SHA-256 2838552d1d554c388465d5deb0a7c5fca1a7e481e72b943c55e32ae80b4362e9 of the research result identify the frozen release; the manifest separately hashes each downloadable file.
Supply comes from a separate CoinGecko 2026-09-26T10:12:20.000Z observation; the separate book package was generated at 2026-09-26T10:14:13.653Z, while the XRP row was observed at 2026-09-26T10:11:09.229Z. Neither is silently inserted as information known to historical cohort investors. No causal claim links community activity or project usage to later return.
| Reproducible file | Contents | Time/interpretation boundary |
|---|---|---|
| Research JSON | /research-data/hot-coin-profiles/2026-09-26-v1/xrp.json | Calculation version, summary and full paired cohort |
| Observation CSV | /research-data/hot-coin-profiles/2026-09-26-v1/xrp-monthly-observations.csv | 57 matched monthly starts |
| Asset daily inputs | /research-data/hot-coin-profiles/2026-09-26-v1/xrp-daily-inputs.csv | Event, observation and ingestion dates |
| BTC daily inputs | /research-data/hot-coin-profiles/2026-09-26-v1/btc-daily-inputs.csv | Matched BTC daily opens and provenance |
| Excluded starts | /research-data/hot-coin-profiles/2026-09-26-v1/xrp-exclusions.csv | 0 missing pairs; header retained if zero |
| Supply source | /research-data/hot-coin-profiles/2026-09-26-v1/coingecko-supply-source.json | Dated provider fields, not a historical feature |
| Order-book source | /research-data/hot-coin-profiles/2026-09-26-v1/orderbook-source.json | Sampled current market, may omit this asset |
Verify: CoinNudge frozen spot-path research · Complete monthly observation ledger · Daily historical input ledger · Matched BTC daily input ledger · Frozen CoinGecko supply response · Dated order-book source · Social directory and limitations · XRP Ledger: what is XRP? · XRPL escrow mechanics · XRPL transaction costs
Take the next step with this evidence.
Choose ongoing Telegram monitoring or inspect structured data in your own research workflow.
Receive qualifying events in Telegram.
Use the ready-made alert checklist, message explanations and daily briefing. Check the supported categories and coins before subscribing; every Research page is not a separate alert category.
Check the alert list · View alert plans
Inspect the data before choosing a pack.
Prepared research packs supply scoped features, separate outcomes where available and quality flags. Buy a fixed edition once and download directly; API use is optional.
Check data pack samples · Explore the full data catalog · Compare data plans
Each purchased pack includes its specified fields and published date range. This page's full dataset is not automatically included. Other data families require coverage, date, field and source-use confirmation before purchase. Telegram Pro is a separate 30-day service; historical packs are one-time purchases.
Frequently asked questions
What is XRP coin (XRP Ledger) used for?
XRP is the native currency of the XRP Ledger. It pays transaction costs and can be used as a bridge asset, but owning XRP is not owning Ripple or its payment business. This answers the token's documented role, not whether its price is attractive.
Is XRP worth holding?
There is no unconditional yes in this dated research. A credible XRP holding case needs independently measured XRP-specific payment demand and a dated escrow/float analysis; Ripple business growth by itself is insufficient. The historical 57 monthly 90-day starts overlap, and 20/57 beat BTC; this is not a future success rate. Check your own horizon, loss limit and live evidence before deciding.
Is XRP a good coin to buy now?
This report is not a personalized buy call. The latest dated 90-day XRP path was +46.3% versus BTC +40.5%, but only 20/57 earlier 90-day monthly starts beat BTC and rights, supply and execution still matter.
How has XRP performed over 7, 30, 90 and 365 days?
The matched Binance spot daily-open returns are 7 days +18.4%; 30 days +7.0%; 90 days +46.3%; 365 days −47.5% through September 25, 2026. These are dated historical windows, not live quotes.
Does buying XRP make me a Ripple shareholder?
No. XRP is a ledger asset, not Ripple equity or a claim on its business revenue.
Does a monthly Ripple escrow release mean immediate selling?
No. Release eligibility, completion, relocking, custody transfer and exchange sale are distinct events.
Do all Ripple payments require XRP?
No blanket claim is supported. Confirm the exact product and settlement route before measuring XRP demand.
Can I reproduce this XRP study?
Yes. The page exposes every 57 matched 90-day start, the daily input CSV, exclusions, version and hashes. The windows overlap, so observed counts are not independent future probabilities.
Does XRP trading volume guarantee easy execution?
No. The 30-day Binance spot turnover is separate from one sampled order book. At the cited snapshot the returned ±1% book depth was $4,161,327; later depth and actual fills can differ.
Does XRP payment volume equal permanent XRP buying demand?
No. Bridge units may be reused. Assess the route's XRP inventory and holding duration as well as throughput; this frozen price study has not measured those balances.
Is an XRP exchange deposit proof of selling?
No. A transfer, custody change and executed sale are distinct events. Without trade or recipient evidence, do not equate a deposit with immediate market selling.
What are XRP tokenomics?
XRP has no normal mining issuance; fees are burned. Ripple escrow releases change access to existing inventory, not protocol minting. A released amount is not automatically sold, and XRP ownership is not Ripple equity.
Sources and verification
- CoinNudge frozen spot-path researchMatched daily-open returns, full cohort and audit hashes.
- Complete monthly observation ledgerEvery eligible 90-day matched start.
- Daily historical input ledgerActual daily inputs with observation and ingestion time.
- Matched BTC daily input ledgerThe same-date BTC opens used in every paired return and drawdown.
- Frozen CoinGecko supply responseProvider-defined current float, total and maximum supply at its own timestamp.
- Dated order-book sourceSampled Binance books for covered markets; not the entire exchange.
- Social directory and limitationsDirectional 7-day X and 30-day Reddit mention counts; bot and promotion filtering unverified.
- XRP Ledger: what is XRP?Native asset, company distinction and escrow context.
- XRPL escrow mechanicsEligibility and completed release are different.
- XRPL transaction costsTransaction fees are destroyed.
Monitor XRP market changes without treating a dated report as a current order.
Use this report for the thesis and risk checks, then verify current liquidity and any alert separately.
Preview Telegram alert coverage