Single-coin evidence report · By CoinNudge Research · · Guide updated 2026-10-03 · 20 min read
What is Plasma (XPL) coin, and is it worth holding?
Plasma (XPL) coin is the native token of a stablecoin-focused chain, not a claim on outstanding stablecoin balances. Market evidence ends at the 2026-09-26 UTC daily open; supply and operating records have separate dates below. XPL gained +13.5% over the last dated 90 days but lagged BTC’s +40.1% same-date gain; its available 365-day daily-open path was −91.0% with a −96.2% peak-to-trough drawdown. The nine 90-day monthly starts remain exploratory. Stablecoin transfers alone do not establish XPL value capture, especially when gas is sponsored or paid through another token. Direct Plasma chain snapshots show $872,826,408 USD₮0 outstanding at the cutoff, +9.3% versus four weeks earlier but −5.9% versus 13 weeks earlier; this is one stablecoin's stock, not verified XPL purchases.
See the research evidence · Check live market context
Quick answer: XPL coin in three checks
- Plasma (XPL) coin is the native token of a stablecoin-focused chain, not a claim on outstanding stablecoin balances. Market evidence ends at the 2026-09-26 UTC daily open; supply and operating records have separate dates below. XPL gained +13.5% over the last dated 90 days but lagged BTC’s +40.1% same-date gain; its available 365-day daily-open path was −91.0% with a −96.2% peak-to-trough drawdown. The nine 90-day monthly starts remain exploratory. Stablecoin transfers alone do not establish XPL value capture, especially when gas is sponsored or paid through another token. Direct Plasma chain snapshots show $872,826,408 USD₮0 outstanding at the cutoff, +9.3% versus four weeks earlier but −5.9% versus 13 weeks earlier; this is one stablecoin's stock, not verified XPL purchases.
- Historical coverage: 367 daily opens; 9 complete 90-day monthly starts. 90-day cohort remains exploratory.
- Token-specific question: Do stablecoin transfers on Plasma require durable XPL demand when gas can be sponsored or abstracted?
What does Plasma do for stablecoins, and what is XPL used for?
Plasma is a stablecoin-focused chain and XPL is its native token for network security and gas-related economics. Stablecoin activity may grow without every user personally buying XPL because sponsored and alternative-gas routes exist.
The investor question is: Do stablecoin transfers on Plasma require durable XPL demand when gas can be sponsored or abstracted? This report tests what the token does, what it does not entitle a holder to, how supply can change and what actual dated spot paths showed. Price history is not used as proof that product use caused the move.
| XPL research check | Observed or documented answer | Evidence boundary |
|---|---|---|
| Token and project | Plasma is a stablecoin-focused chain and XPL is its native token for network security and gas-related economics. Stablecoin activity may grow without every user personally buying XPL because sponsored and alternative-gas routes exist. | Business success and tokenholder benefit differ |
| Available local/venue daily opens | 367 from 2025-09-25 to 2026-09-26 | local archive, potentially retrospective backfill |
| Current chart | 90 matched UTC days vs BTC | Historical opens, not a live quote |
| Provider-estimated circulating supply | 4,533,333,333 | CoinGecko 2026-09-27T02:55:20.000Z |
Verify: Plasma mainnet and XPL issuer announcement · Plasma official gas abstraction overview
Who pays for zero-fee USDT transfers if users do not buy XPL?
Sponsored or alternative-gas paths mean users do not necessarily buy XPL themselves for each USDT transfer. Plasma’s official mainnet materials describe XPL as a native token for validator incentives and a network built around stablecoin movement. The network also advertises zero-fee USDT transfers. Its current docs describe sponsored gas from a foundation allowance and an ERC-20 paymaster supporting other approved gas tokens. Therefore, transaction growth is not automatically a one-for-one XPL purchase requirement.
The relevant token-capture test is actual XPL spent or staked, foundation-sponsored allowance usage, validator rewards and net supply changes per transaction cohort. Stablecoin balances, transfers or app integrations are useful product metrics but are not tokenholder distributions or a direct valuation formula.
The owner of a token, user of a product, operator earning incentives and shareholder of a company can be different parties. The table below keeps their claims separate instead of transferring a product benefit to every XPL wallet.
Reconcile actual gas payer → XPL consumed or retained → any burn → validator issuance and circulating change over the same interval. USD₮0 totalSupply belongs to another token ledger and cannot substitute for XPL purchases. Missing payer or issuance fields block a quantitative net-demand conclusion.
| Role | What the source supports | What it does not establish |
|---|---|---|
| XPL holder | Holds Plasma native token and may participate under network rules | No direct ownership of all stablecoins held on the chain |
| USDT transfer user | May benefit from sponsored or zero-fee transfer routes | No requirement to personally buy and hold XPL on every transfer |
| Validator or staker | May participate in network security and rewards | Reward terms and lock risk differ from passive spot ownership |
Verify: Plasma mainnet and XPL issuer announcement · Plasma official gas abstraction overview
How does 4.53 billion circulating XPL compare with 10 billion total?
The frozen 4.53-billion circulating estimate is below 10-billion total supply; the gap is not a dated sell-pressure forecast. The frozen provider snapshot estimates 4.53 billion XPL circulating from 10 billion total. That gap is potential future float context, not a complete unlock calendar. The issuer reports a public-sale allocation and separate community distributions; this page does not turn those announcements into a dated forecast of sell pressure without a current official schedule and completed transfer audit.
A buyer should compare possible incremental circulating units with daily executable depth, not just total USDT movement on Plasma. Sponsored gas may improve user experience while weakening a simple “more transfers equals more XPL demand” argument. Which party ultimately buys and consumes XPL must be observed.
The 2026-09-27T02:55:20.000Z CoinGecko snapshot lists 4,533,333,333 circulating XPL, 10,000,000,000 total and no reported maximum. A reported stock difference is not an unlock event, a date or a sell order. Actual vesting rules and transfer records need a separate dated check.
| Supply or valuation field | Frozen value | Use correctly |
|---|---|---|
| Circulating units | 4,533,333,333 | Provider estimate; not an on-chain audit |
| Total units | 10,000,000,000 | Do not substitute for current float |
| Maximum units | Not reported | Missing maximum is not zero |
| Market capitalization | $497,100,522 | Price × provider circulating amount |
| Fully diluted valuation | $1,096,545,269 | Scenario stock value; not near-term selling amount |
Verify: Original provider snapshot · Plasma mainnet and XPL issuer announcement · Plasma official gas abstraction overview
Does rising on-chain USD₮0 supply create direct XPL demand?
No direct XPL demand follows from the measured USD₮0 stock alone. We queried the USD₮0 contract identified by its issuer on Plasma at 14 prespecified Saturday UTC boundaries. Contract totalSupply was $927,381,073 thirteen weeks before the cutoff, $798,440,305 four weeks before and $872,826,408 at the cutoff. The four-week change was $74,386,103 (+9.3%). Every snapshot records the Plasma block and raw six-decimal token units. This is direct observation of one token's outstanding units; it is not the entire stablecoin universe on Plasma.
Outstanding USD₮0 is a stock. Bridging, minting and burning can change it without implying new unique users, payments or transaction throughput. Plasma also documents sponsored and alternative-gas routes, so a growing USD₮0 balance does not mean every sender personally acquired XPL. No user-versus-sponsor gas payer series, XPL burn ledger or validator issuance reconciliation is in this release.
The next token-capture test is an aligned ledger of gas payer type (user, foundation sponsor or paymaster), actual XPL consumed and burned, validator issuance and net circulating change. Until those can be reconstructed, chain activity is partly observable but the strength of the XPL investment mechanism remains unproved.
| XPL operating / token-capture test | Dated evidence | What it can prove |
|---|---|---|
| Plasma USD₮0 supply, cutoff / four weeks prior | $872,826,408 / $798,440,305 | One ERC-20 token stock, not transfer flow |
| Plasma USD₮0 supply, 13 weeks prior | $927,381,073 | Latest is below this older level |
| User-paid versus sponsored XPL gas | Not independently split | Cannot infer who bought XPL |
| XPL burn, rewards and net issuance | Not reconciled in this release | No holder-income or deflation claim |
Verify: Frozen operating-evidence record · 14 weekly Plasma contract-state observations · USD₮0 issuer contract identification · Plasma gas-abstraction rules
How did Plasma USD₮0 supply change across 14 UTC weeks?
The 14 weekly snapshots show a four-week USD₮0 recovery, not uninterrupted growth or XPL fee capture. Each row is the last Plasma block at or before the stated Saturday 00:00 UTC boundary. The block number and full hash in the downloadable file identify the exact historical state; token units come directly from ERC-20 totalSupply. These snapshots were retrieved retrospectively and are not claimed to have been recorded by CoinNudge at the original time.
The later four-week increase does not erase the lower level versus 13 weeks earlier. Supply can change through bridge mint/burn and does not count transfers, fee payers or XPL consumption.
| UTC snapshot | USD₮0 outstanding | Change from prior week | Plasma block |
|---|---|---|---|
| 2026-06-27 | $927,381,073 | First observation | 25578071 |
| 2026-07-04 | $910,325,463 | −1.8% | 26182865 |
| 2026-07-11 | $828,971,683 | −8.9% | 26787647 |
| 2026-07-18 | $742,259,671 | −10.5% | 27392447 |
| 2026-07-25 | $742,608,496 | +0.0% | 27997244 |
| 2026-08-01 | $775,028,202 | +4.4% | 28601974 |
| 2026-08-08 | $695,431,201 | −10.3% | 29206772 |
| 2026-08-15 | $650,586,785 | −6.4% | 29811454 |
| 2026-08-22 | $726,777,861 | +11.7% | 30416249 |
| 2026-08-29 | $798,440,305 | +9.9% | 31021038 |
| 2026-09-05 | $633,959,490 | −20.6% | 31625833 |
| 2026-09-12 | $708,258,379 | +11.7% | 32230633 |
| 2026-09-19 | $719,400,413 | +1.6% | 32835409 |
| 2026-09-26 | $872,826,408 | +21.3% | 33439864 |
Verify: Complete on-chain snapshot JSON · Complete on-chain snapshot CSV
Why did XPL’s latest bounce coexist with a weak one-year path?
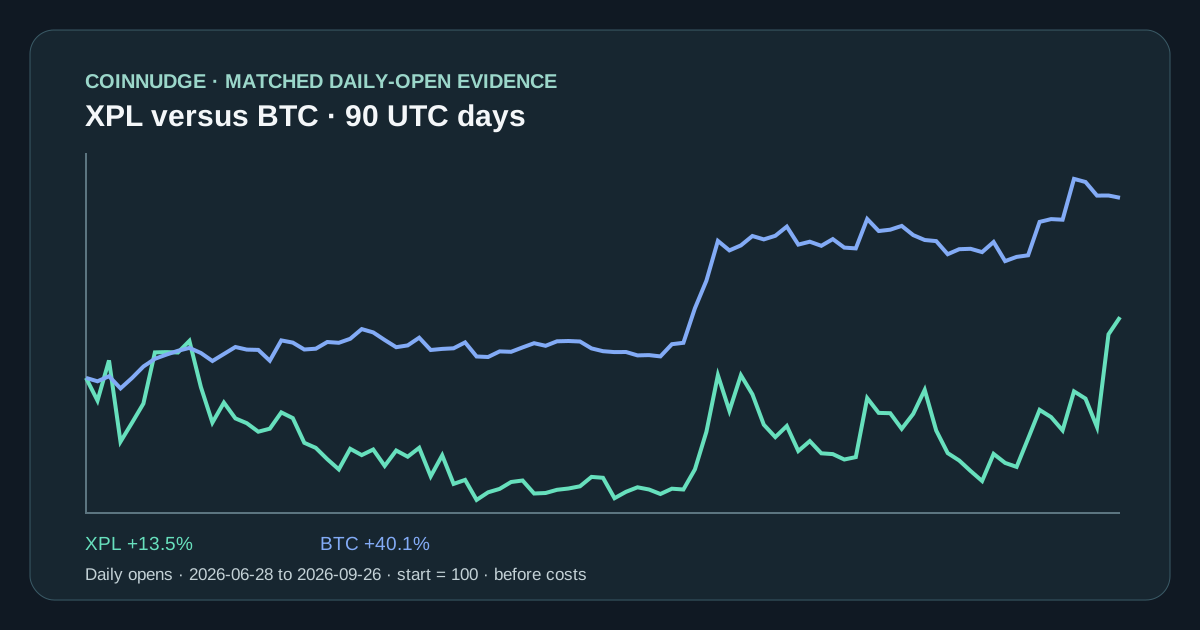
The latest +13.5% 90-day rebound did not erase the −91.0% available 365-day return; entry date and path matter. The September 26 UTC-open 90-day return was +13.5% versus BTC +40.1%; the asset’s same-window daily-open peak-to-trough drawdown was −32.7%. This is one end-date path, not a 90-day expected return.
The line chart normalizes XPL and BTC to 100 at the same UTC start, making relative direction visible without pretending that the two assets have comparable unit prices. Both asset and BTC come from Binance USDT spot daily opens. Intraday low, spread, fees and actual execution can produce a worse realized experience than the line shows.
| Holding window | XPL spot return | BTC spot return | XPL − BTC | Asset path drawdown |
|---|---|---|---|---|
| 7 days | +22.2% | +4.0% | +18.2 pp | −8.2% |
| 14 days | +39.1% | +8.9% | +30.2 pp | −8.2% |
| 30 days | +30.7% | +6.4% | +24.3 pp | −20.8% |
| 60 days | +45.3% | +31.9% | +13.4 pp | −23.4% |
| 90 days | +13.5% | +40.1% | −26.6 pp | −32.7% |
| 180 days | +32.4% | +27.4% | +5.0 pp | −56.5% |
| 365 days | −91.0% | −22.8% | −68.2 pp | −96.2% |
Verify: Full frozen return inputs
Did XPL beat BTC across its nine full 90-day entry months?
Across nine complete monthly 90-day XPL starts, two beat BTC; median XPL return was −15.4%, and all nine had deeper daily-open drawdowns than BTC. Nine overlapping starts are exploratory, not dependable purchase odds. The separate 50-start weekly 14-day cohort has a −7.4% median and 18 BTC-beating paths; it answers a shorter question and is not pooled with the nine 90-day starts.
We predefine calendar-first 90-day and 30-day starts plus Monday 14-day starts from the first available daily bar through the last date that permits a complete exit on 2026-09-26. Every candidate must have each asset and BTC daily open in the path. We neither choose a favorable entry date nor fill a missing day with zero. The three cohorts answer different holding-horizon questions; they are not pooled into a single success rate.
The auxiliary 14-day starts overlap. An every-second-week subset has 25 observations and eight BTC-beating paths: a dependence sensitivity, not an independent win-rate estimate. Keep horizon and candidate schedule attached to every statistic.
| Prespecified cohort | Complete / candidates | XPL median | Beat BTC | Deeper drawdown | Reading status |
|---|---|---|---|---|---|
| monthly 30d | 11/11 | −9.9% | 3/11 | 11/11 | Exploratory: n<20 |
| monthly 90d | 9/9 | −15.4% | 2/9 | 9/9 | Exploratory: n<20 |
| weekly 14d | 50/50 | −7.4% | 18/50 | 50/50 | Descriptive; dependent windows |
Verify: Full candidate and outcome dataset · Excluded/missing ledger
Did the auxiliary 14-day XPL paths depend on the prior BTC month?
The auxiliary 50-start 14-day sample was weaker after nonnegative prior BTC months: median XPL return −11.0% (24 starts), versus −3.6% after negative months (26 starts). This is a descriptive short-horizon split, not the nine-start 90-day study or a rule to buy after BTC declines.
For these 14-day weekly starts, the state is the preceding 30-day BTC daily-open return, using only observations before entry. The groups sum to 50, but overlap and common market exposure limit independence. The complete CSV identifies horizons and dates. The next section returns to the separate 90-day monthly cohort.
| Prior BTC 30d state | n | XPL median | XPL beat BTC |
|---|---|---|---|
| Prior BTC 30d ≥ 0 | 24 | −11.0% | 5/24 |
| Prior BTC 30d < 0 | 26 | −3.6% | 13/26 |
| Prior BTC unavailable | 0 | — | — |
Which of the nine 90-day XPL starts contradicted a simple recovery thesis?
The table shows all nine complete monthly 90-day XPL starts, not 14-day observations. The worst BTC-relative case began 2025-10-01: XPL −84.4% versus BTC −23.5%, with −88.5% XPL daily-open drawdown. The strongest counterexample began 2026-04-01: XPL +13.0% versus BTC −11.8%, yet XPL path drawdown was −56.5%. Both belong to the frozen prespecified cohort.
A relative gain is not necessarily an absolute gain: the 2026-05-01 path beat BTC by +0.8 percentage points while XPL fell −15.4%. Read date, horizon, return and drawdown together; two BTC-beating paths do not turn nine dependent observations into reliable purchase odds.
| UTC entry | Horizon | XPL return | BTC return | XPL − BTC | XPL drawdown |
|---|---|---|---|---|---|
| 2025-10-01 | 90d | −84.4% | −23.5% | −60.9 pp | −88.5% |
| 2025-11-01 | 90d | −58.6% | −22.8% | −35.8 pp | −64.5% |
| 2025-12-01 | 90d | −48.7% | −25.9% | −22.8 pp | −62.2% |
| 2026-01-01 | 90d | −42.5% | −22.1% | −20.4 pp | −62.2% |
| 2026-02-01 | 90d | −14.3% | −0.6% | −13.6 pp | −35.3% |
| 2026-03-01 | 90d | −12.6% | +9.7% | −22.3 pp | −42.2% |
| 2026-04-01 | 90d | +13.0% | −11.8% | +24.8 pp | −56.5% |
| 2026-05-01 | 90d | −15.4% | −16.2% | +0.8 pp | −44.4% |
| 2026-06-01 | 90d | −2.8% | +6.2% | −8.9 pp | −34.8% |
Verify: Download all cohort rows
Can large XPL positions exit without moving the market?
The frozen $10,763,509 median daily Binance turnover cannot guarantee a large XPL exit near a quote. XPL’s archived Binance Spot USDT daily candles have 30 valid quote-turnover days in the last 30. Their median daily quoted turnover is $10,763,509. This is an amount traded throughout a day, not the amount available at the current bid, and it does not prove a $10,000 or institutional-size order can be executed near a headline price.
The evidence in this release does not include a synchronized, venue-specific level-two book for XPL. We therefore do not report a fabricated current spread, ±1% depth or expected slippage. Before taking action, inspect the live order book, trade size, market impact, available pairs and withdrawal conditions on the actual venue.
Before an actual XPL trade, compare intended size with fresh bids/asks on the same venue and estimate entry plus exit fees and adverse slippage. Repeat after a material price move. If the fill estimate is missing or exceeds the loss budget, reduce proposed size or wait. This is an execution-check method, not a fill simulation performed in the frozen study.
| Execution question | Observed answer | Missing check |
|---|---|---|
| 30-day median daily quote turnover | $10,763,509 | Not executable depth |
| Venue | Binance Spot USDT | Check the intended trading venue |
| Live bid/ask spread | Not sampled for this release | Capture a fresh order book |
| $10,000 round-trip costs | Not estimated | Include exchange fees, slippage and funding if leveraged |
Verify: Current multi-market liquidity study · Dated venue candle inputs
Are Plasma stablecoin deposits evidence of XPL tokenholder income?
No: stablecoin deposits are product-activity observations, not income distributed to XPL holders. The Plasma narrative can combine stablecoin adoption, low-fee transfers, launch liquidity and XPL price in a single sentence. Keep four ledgers: stablecoin deposits, genuine paying users, XPL used for security/gas, and tradable XPL supply. A rise in the first two does not prove improvement in the latter two.
This release has no verified count of unique social users or independently filtered sentiment. A trending placement or message volume could include promotions, repeated posts or ticker collisions. We use community discussion to identify claims to test, not as a measured demand or tokenholder-income variable.
Verify: Plasma mainnet and XPL issuer announcement · Plasma official gas abstraction overview
What would make an XPL holding thesis stronger than the chain narrative?
XPL remains a conditional gas-and-security thesis; stablecoin activity alone does not verify tokenholder value capture. The evidence does not justify an unconditional “buy” or “sell.” The stronger case would be: Audited, recurring XPL consumption or durable staking demand grows alongside genuine stablecoin users and exceeds new tradable supply pressure. The weaker case would be: Most activity uses sponsored or alternative gas with limited XPL demand, while float expands and the token remains prone to drawdowns.
A practical holding checklist is to define a time horizon, the project-to-token mechanism, next supply milestone, position size and acceptable drawdown. Decide what observation would falsify the thesis. Even the larger historical cohort is descriptive, overlapping and vulnerable to survivorship and regime changes. For historical opportunity cost, use the nine monthly 90-day starts as the longer-holding main cohort; the table’s 50 weekly 14-day starts refer only to the auxiliary shorter-horizon analysis. Their denominators are not interchangeable.
Separate user-paid gas, sponsor/paymaster gas, staking demand, validator rewards and tradable supply changes for an XPL thesis. Require aligned observations before claiming stablecoin growth absorbs XPL. If activity grows but payer and issuance ledgers are missing, retain research-watchlist status rather than label the mechanism verified.
| Decision gate | Evidence to request | Failure sign |
|---|---|---|
| Token-specific value capture | Do stablecoin transfers on Plasma require durable XPL demand when gas can be sponsored or abstracted? | Only project growth is shown |
| Supply and float | Official allocation plus actual transfers | Unmeasured release reaches market |
| Historical opportunity cost | 50 complete 14-day weekly starts versus BTC | Single rally is treated as a general rule |
| Execution | Fresh venue depth, size and fees | Quoted price cannot be filled |
| Thesis invalidation | Most activity uses sponsored or alternative gas with limited XPL demand, while float expands and the token remains prone to drawdowns. | No observable reassessment trigger |
Verify: Frozen XPL operating evidence · Complete XPL paired-price study
How were XPL daily paths matched with BTC and token economics separated?
Calculation single-coin-paired-paths-20260927-1.0; daily-open endpoint 2026-09-26 UTC; coverage 2025-09-25–2026-09-26. The asset’s historical source is local archive, potentially retrospective backfill. This is retrospective market research, not a claim that CoinNudge observed every older bar in real time.
XPL uses Binance XPL/USDT and BTC uses Binance BTC/USDT; both are paired at the same UTC daily open. Recent endpoints use 7/14/30/60/90/180/365 daily-open intervals only when all intermediate opens exist. Cohorts use every calendar month-first 30/90-day start and every Monday 14-day start from first available bar, with complete paired paths only. No strategy, fees, spreads, taxes, staking or causal token-use inference. Overlapping windows are dependent; fewer than 20 rows is exploratory. Historical archive/API retrieval is not proof the data was locally known at the original event time. Returns equal end open divided by start open minus one. BTC-relative differences are percentage points. Drawdown is the minimum of path value divided by its prior peak minus one. Candidate starts and all outcomes are preserved; a missing path is null, never a zero return.
The release exposes the calculation inputs, field dictionary, 70 observed cohort rows, 0 excluded candidates, source supply snapshot and SHA-256 input/output identities. Data from CoinGecko and project documents have their own timestamps and are not inserted as features known at a historical start. An independent rerun should match the downloadable rows before interpreting the prose.
Editing updated 2026-10-03: clarified section answers, holding decisions and evidence scope only. September frozen datasets, formulas, sample counts, charts and method version remain unchanged; the editing date is not a new market observation.
| Reproduction file | Purpose | Boundary |
|---|---|---|
| Research JSON | /research-data/hot-coin-profiles/2026-09-27-v1/xpl.json | Summary, version and hashes |
| All outcome rows | /research-data/hot-coin-profiles/2026-09-27-v1/xpl-observations.csv | Every candidate that passed paired coverage |
| Missing/excluded starts | /research-data/hot-coin-profiles/2026-09-27-v1/xpl-exclusions.csv | Explicit absent pairs; no invented zeroes |
| Asset daily inputs | /research-data/hot-coin-profiles/2026-09-27-v1/xpl-daily-inputs.csv | Unrounded venue observations |
| BTC daily inputs | /research-data/hot-coin-profiles/2026-09-27-v1/btc-daily-inputs.csv | Same-date comparator |
| Field dictionary | /research-data/hot-coin-profiles/2026-09-27-v1/field-dictionary.json | Deterministic formulas and status |
| Release manifest | /research-data/hot-coin-profiles/2026-09-27-v1/manifest.json | SHA-256 of frozen files |
Verify: CoinNudge frozen paired-price study · All matched outcome rows · All asset daily inputs · Same-date BTC daily inputs · Missing-pair ledger · Frozen CoinGecko supply snapshot · Field dictionary and calculation contract · Plasma mainnet and XPL issuer announcement · Plasma official gas abstraction overview · Frozen operating-evidence record
Take the next step with this evidence.
Choose ongoing Telegram monitoring or inspect structured data in your own research workflow.
Receive qualifying events in Telegram.
Use the ready-made alert checklist, message explanations and daily briefing. Check the supported categories and coins before subscribing; every Research page is not a separate alert category.
Check the alert list · View alert plans
Inspect the data before choosing a pack.
Prepared research packs supply scoped features, separate outcomes where available and quality flags. Buy a fixed edition once and download directly; API use is optional.
Check data pack samples · Explore the full data catalog · Compare data plans
Each purchased pack includes its specified fields and published date range. This page's full dataset is not automatically included. Other data families require coverage, date, field and source-use confirmation before purchase. Telegram Pro is a separate 30-day service; historical packs are one-time purchases.
Frequently asked questions
What is XPL coin used for?
Plasma is a stablecoin-focused chain and XPL is its native token for network security and gas-related economics. Stablecoin activity may grow without every user personally buying XPL because sponsored and alternative-gas routes exist. Documented use is not a guaranteed token price or holder income.
Is XPL coin worth holding based on this evidence?
Plasma (XPL) coin is the native token of a stablecoin-focused chain, not a claim on outstanding stablecoin balances. Market evidence ends at the 2026-09-26 UTC daily open; supply and operating records have separate dates below. XPL gained +13.5% over the last dated 90 days but lagged BTC’s +40.1% same-date gain; its available 365-day daily-open path was −91.0% with a −96.2% peak-to-trough drawdown. The nine 90-day monthly starts remain exploratory. Stablecoin transfers alone do not establish XPL value capture, especially when gas is sponsored or paid through another token. Direct Plasma chain snapshots show $872,826,408 USD₮0 outstanding at the cutoff, +9.3% versus four weeks earlier but −5.9% versus 13 weeks earlier; this is one stablecoin's stock, not verified XPL purchases. This is dated non-personalized research, not a trade instruction.
How did XPL perform versus Bitcoin?
Across the frozen 90-day same-UTC daily-open window, XPL returned +13.5% and BTC returned +40.1%. Historical paths do not forecast the next period.
How much historical XPL data is available?
This release covers 367 asset daily opens from 2025-09-25 through 2026-09-26 on Binance Spot USDT. Backfills and public API retrieval are retrospective, not original-date CoinNudge observations.
Does every zero-fee USDT transfer make someone buy XPL?
No. Plasma documents sponsored and alternative-gas paths. Measure actual XPL consumption or staking rather than inferring it from transfer count.
Is 10 billion XPL circulating today?
No. The frozen provider estimate is about 4.53 billion circulating of 10 billion total, with method and date limitations.
Does a recent XPL bounce mean its long-term loss is recovered?
No. The latest 90-day return and available 365-day drawdown describe very different entry dates and paths.
Do larger Plasma USD₮0 balances guarantee XPL demand?
No. Direct contract snapshots show the outstanding supply of one stablecoin, but sponsored/alternative gas, burn, validator rewards and net XPL issuance are not reconciled here.
Can I verify the XPL calculations?
Yes. The full JSON, 70 cohort rows, daily input files, field dictionary, exclusion ledger and manifest are linked on the page.
What evidence should I check before holding XPL?
Separate user-paid gas, sponsor/paymaster gas, staking demand, validator rewards and tradable supply changes for an XPL thesis. Require aligned observations before claiming stablecoin growth absorbs XPL. If activity grows but payer and issuance ledgers are missing, retain research-watchlist status rather than label the mechanism verified.
Why are there nine 90-day XPL starts but 50 short-period observations?
Monthly 90-day starts supply the nine-row holding table; Monday 14-day starts supply the 50-row auxiliary state analysis. Do not add their denominators or apply a 14-day state result to a 90-day holding rule.
Sources and verification
- CoinNudge frozen paired-price studyVersion, full summary, all observations and hashes
- All matched outcome rowsComplete monthly and weekly cohort ledger
- All asset daily inputsUnrounded source opens, turnover and provenance
- Same-date BTC daily inputsBTC comparator candles
- Missing-pair ledgerExplicit rejected candidates, empty if none
- Frozen CoinGecko supply snapshotProvider-defined supply and timestamp
- Field dictionary and calculation contractPrecise formulas and missing-value semantics
- Plasma mainnet and XPL issuer announcementXPL role, public sale and initial community allocations
- Plasma official gas abstraction overviewSponsored XPL gas and ERC-20 paymaster mechanism
- Frozen operating-evidence record
Follow XPL conditions with transparent market context.
Use this historical report to frame your questions, then check current liquidity, supply and Telegram alerts separately.
Explore alert coverage